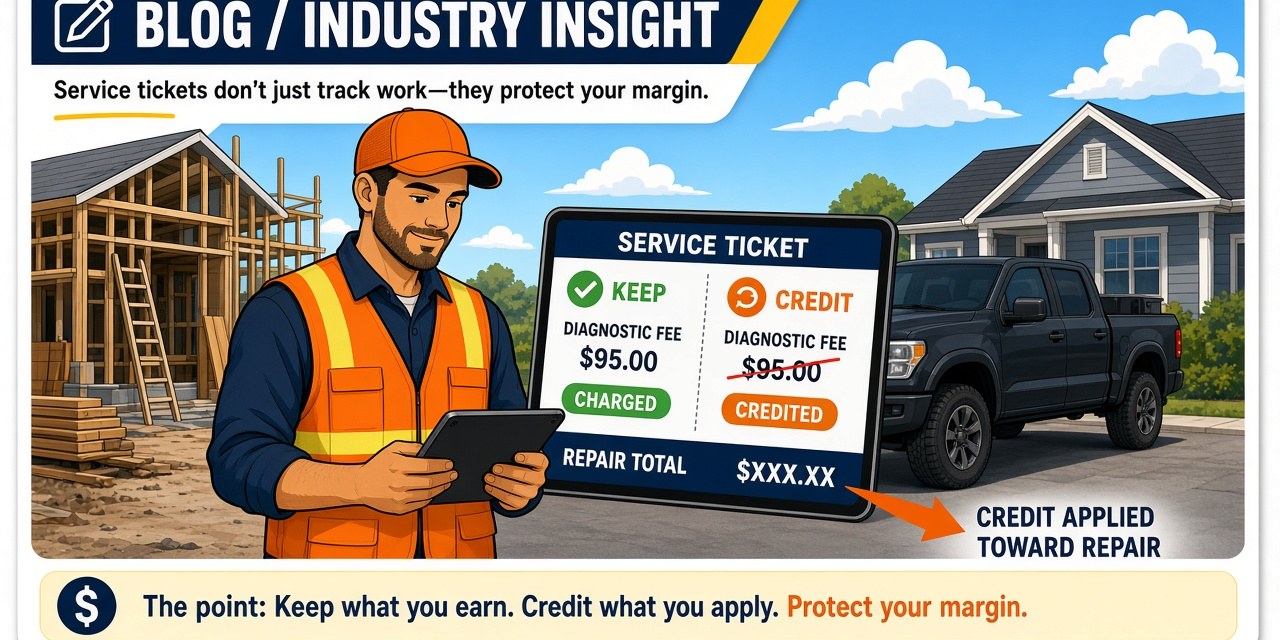
If you credit the diagnostic fee when the customer approves the repair, you need to know whether the repair is big enough to absorb that credit and still hit your margin — or whether you just gave away the only profitable hour on the ticket. The answer depends entirely on the numbers, not on what feels fair in the moment.
This article shows the same-visit credit math in full: what a diagnostic visit costs you, what margin looks like when you keep the fee versus when you credit or waive it, and how a partial credit splits the difference. It also covers the one move most contractors miss — raising the repair price when crediting, so the credit doesn't come out of your pocket.
For how to structure trip fees and travel billing in the first place, see should contractors charge for drive time. For HVAC diagnostic fee policy and credit-toward-repair conventions in that trade, see the HVAC job pricing guide. This article is only the credit math.
What a Diagnostic Fee Actually Is
A diagnostic fee — sometimes called a service call fee, trip charge, or assessment fee — is what you charge for a paid visit that identifies a problem before any repair begins. The customer pays for your time, your drive, and your expertise. The repair, if they approve it, is a separate transaction.
That separation matters. The diagnostic visit has its own labor hours, its own drive cost, and its own overhead. It's a billable job whether or not a repair follows. When you run the numbers, you'll often find the diagnostic hour is one of your more profitable hours — a flat fee for defined, bounded work with no materials exposure and a predictable time commitment.
The confusion starts when both happen on the same visit. You diagnose the problem and the customer approves the repair right there. Now you have two distinct cost events — the diagnostic pass and the repair pass — but one visit, one truck, and one customer who may have expected the diagnostic fee to disappear once they said yes.
Whether it should disappear is a business decision, not a courtesy. It depends on whether the repair ticket is large enough to carry both costs and still land at your margin target.
The Same-Visit Credit Math
Here is a full worked example. All dollar figures are made-up and labeled as such. Substitute your own rates.
Pass 1 — Price the Diagnostic Visit Alone
Run this in the Job Profit Calculator as its own ticket before you even know whether a repair is coming.
The diagnostic earns a 21.8% margin on its own. If the customer declines the repair and you leave, you walk out with $36 in profit on a $165 ticket. That's a real, earned number — not a consolation prize. The diagnostic was a profitable job.
Pass 2 — Price the Repair Ticket
Now the customer approves the repair. Run a second pass in the calculator — repair only, no second drive (you're already on-site).
So you have a $165 diagnostic fee and an $845 repair ticket. Now look at what happens to the combined job under each option.
Option A — Keep the Diagnostic Fee as a Separate Line
Combined margin lands at 32.9% — just under target because the diagnostic alone runs below 35%, but both jobs are individually profitable and nothing was given away.
Option B — Credit the Full Diagnostic Fee Toward the Repair
You keep the $845 repair price on the invoice but subtract the $165 diagnostic as a credit. The customer pays $680 for the repair, having already paid $165 for the diagnostic — $845 total.
By crediting the $165 fee, your total revenue dropped from $1,010 to $845 — but your costs stayed at $678. Margin collapsed from 32.9% to 19.8%. The diagnostic cost is still in your books. You just didn't charge for it.
The math in one line: Crediting the diagnostic fee reduces your revenue by the full fee amount. Your costs do not change. Every dollar you credit comes directly out of profit.
Option C — Partial Credit
Credit half: $82 toward the repair. Customer pays $165 + $763 = $928. Costs unchanged at $678. Profit: $250 (26.9% margin). You kept most of the diagnostic revenue while giving the customer something for saying yes same-day. The margin is between Options A and B — not as strong as keeping it, better than full waiver.
Option D — Credit the Fee, Raise the Repair to Absorb It
This is the move most contractors miss. If you want to credit the $165 diagnostic and still hit 35% margin on the combined job, raise the repair invoice so total money collected still covers combined cost at target margin.
With the made-up numbers above, combined cost is $678. At a 35% target margin: $678 ÷ (1 − 0.35) = $678 ÷ 0.65 = $1,043 total revenue needed. The customer already paid $165 for the diagnostic, so the repair invoice before credit must be $1,043 − $165 = $878. You then apply the $165 credit on that invoice: they pay $713 more on the repair, plus the $165 already paid, for $1,043 total.
You can offer a credit and still hit your margin — but only if you raise the repair price to account for it. The credit isn't free. It's a discount. Discounts have to be priced in.
When Crediting Is Rational — and When It Isn't
When Crediting Makes Sense
- High-ticket repair, margin holds after credit: If the repair is a $2,400 equipment replacement, a $165 credit reduces margin from 34% to 28%. That's still a profitable, acceptable outcome, and the credit closes a large job you want on the books.
- You repriced the repair to absorb it (Option D): You built the credit into the repair quote before presenting it. The customer sees a credit, you collect target margin. Everyone wins.
- Customer is on the fence on a high-margin repair: If the repair margin is strong enough that even a full credit doesn't hurt badly, using the diagnostic as a closing tool to get approval that same day has real business value. Mobilizing for a second visit costs drive time, scheduling overhead, and the risk of the customer shopping around. Factor that before you decide.
- Membership or service-plan customer: If your membership explicitly promises diagnostic-fee credits, the credit is already priced into the plan. You're not waiving — you're honoring a commitment you charged for. The math belongs in the plan pricing, not the individual job ticket.
When Keeping the Fee Is Rational
- They declined the repair: The diagnostic did exactly what it was supposed to do. You went out, identified the problem, gave a professional assessment. Keep the fee without hesitation — that's the product you sold.
- Small repair where the diagnostic is the only profitable line: Use a separate cost stack for that ticket — do not reuse the large-repair combined cost. Example (made-up $): same $129 diagnostic visit cost, then a small same-visit repair of 0.5 hr labor ($37.50), $40 materials, $12 markup, and $8.25 overhead = about $98 repair cost, or $227 combined. Keep both fees and you collect $165 + $200 = $365 against $227. Credit the full diagnostic and you collect only $200 against that same $227 — an outright loss. On low-ticket repairs, the diagnostic fee isn't optional padding. It's the job's margin.
- Long drive already spent: If you drove 45 minutes each way for this call, that drive cost is in the ticket regardless of what happens next. See the section on drive time billing for the full structure. The diagnostic fee helps recover travel cost that the repair ticket alone may not cover.
- First visit, unknown customer: You don't owe a credit to someone you've never worked with before. If the repair is priced at margin and the diagnostic was a separate visit, both stand on their own numbers. Offering an unsolicited credit to a new customer just trains them to expect it next time.
How to Model This in the Calculator
The Job Profit Calculator doesn't have a dedicated diagnostic fee field. That's fine. Run it as two separate passes so you know the cost of each event before making the credit decision.
- Run the diagnostic as its own job ticket. Enter: labor hours for the diagnostic visit, 1 worker, your hourly labor rate, no materials, your overhead %, and drive time (one-way minutes, or add to hours). Enter a target margin. The calculator shows your suggested charge. Compare that to your flat diagnostic fee to confirm the fee is covering cost and margin. If your flat fee is below the suggested charge, your diagnostic is underpriced.
- Run the repair as a second, separate ticket — zero drive time. Enter: repair labor hours, workers, hourly labor rate, materials at cost with markup, overhead %, 0 for drive (same visit). Set target margin. Note the suggested repair price. This is Option A — the repair fully priced on its own, diagnostic kept separate.
- To model Option B (full credit): subtract the diagnostic fee from the repair price. Take the repair price from step 2. Subtract your diagnostic fee. That's what the customer would net-pay for the repair if you credit. Now look at the combined revenue ($165 diag + reduced repair) versus the combined cost from both passes. The margin dropdown is your answer.
- To model Option D (credit with repriced repair): work backward from total revenue needed. Add both costs from steps 1 and 2. Divide by (1 − target margin). That's the total revenue you need. Subtract what the customer already paid for the diagnostic. The remainder is what the repair invoice must show before the credit. If the resulting repair price is significantly higher than a fair-market repair price, the credit isn't viable at your target margin — adjust to a partial credit or keep the fee.
Two passes, one decision: Run diagnostic cost in the calculator. Run repair cost in the calculator. Then do the four-line combined math: total revenue under each option versus combined cost. The margin number tells you whether the credit is profitable or a giveaway. Make the decision with numbers in hand, not gut feel at the door.
Partial Credit, Memberships, and First-Time Customers
Partial Credit
A partial credit — crediting $75 of a $165 fee, for example — is mathematically valid and often easier to present than all-or-nothing. You're acknowledging the customer's same-day commitment without absorbing the full diagnostic cost. Present it as a specific dollar amount, not a percentage: "I'll apply $75 of the service call toward the repair." Don't negotiate upward from zero; name a number and hold it.
Size the partial credit so the combined margin lands between Option B and Option A. With the made-up numbers above: crediting $75 gives you $935 total revenue against $678 cost — 27.5% combined margin. Decide whether that's acceptable given the job size, the customer relationship, and whether you want to close same-day.
Membership and Service-Plan Waivers
If your service plan or maintenance contract waives the diagnostic fee for plan members, that credit is already priced into the plan fee. You're not giving anything away on the individual job — you're honoring what the customer paid for. Treat it as a zero-cost line item on the repair ticket, because the cost recovery happened at plan enrollment.
The pricing question is whether your plan fee actually covers the expected number of diagnostic visits over the plan term. That's a plan-pricing calculation, not a per-job decision. If you're running four diagnostic visits per year for a plan customer who paid $149 for the plan, your plan is underpriced — not your diagnostic fee structure.
First-Time vs. Repeat Customer
A repeat customer with a history of approved work — someone who calls you back, pays promptly, and refers others — has different value than a first-time caller. A credit offered to a regular customer as a deliberate relationship gesture is a business decision with a calculable cost. It's different from reflexively crediting every customer who asks. Know which one you're doing.
For first-time customers: price the repair at full margin (Option A or Option D). You have no loyalty history to reward. If the repair is priced correctly, the total ticket is reasonable on its own. Offer a credit only if the repair is large enough that it reads as a genuine gesture — and only after you've confirmed the repair price absorbs it.
Common Mistakes
- Waiving the fee before you know the repair size. "I'll apply the diagnostic to whatever the repair is" — said before you've priced the repair. You just committed to a discount on a number you don't know yet. Run Pass 2 first. Confirm the repair price. Then decide whether the credit is viable.
- Crediting labor you already spent without raising the repair price. The diagnostic hour happened. Your tech drove out there. Overhead ran. That cost is locked in whether or not you charge for it. When you credit the diagnostic fee, your revenue drops by that amount — your costs don't. If you don't raise the repair ticket to compensate, you're subsidizing the credit out of margin.
- Treating trip fee and diagnostic skill as free. Some contractors distinguish between the drive (trip fee) and the diagnostic work (service call fee) and offer to waive only the trip fee. That's a partial credit on the travel cost, not on the skilled diagnostic labor. The problem is the same: drive cost is real cost. If you waive the trip fee on a same-day repair, confirm the repair price covers both the repair cost and the travel cost. If it doesn't, you're paying for the drive yourself.
- Quoting the repair as if the diagnostic never happened. Some contractors price the repair starting from a blank slate — as if the diagnostic visit was a free pre-consultation. The repair is priced at its own cost plus margin, the diagnostic is quietly folded in, and the customer pays less than they would have for two separate line items. This is the most expensive version of the credit mistake because it happens invisibly. You never see it on a margin report. Run both passes so you know what the combined job actually cost.
- Crediting on low-ticket repairs without checking the combined math. On that same small-repair stack (made-up $: about $98 repair cost + $129 diagnostic cost = $227 combined), a $200 repair with a $165 diagnostic credit leaves $200 total collected against $227 in cost — a loss before you even talk margin. Double-check the combined numbers any time the repair ticket is smaller than roughly 2× your diagnostic fee. That's the zone where the credit can eliminate all margin or create an outright loss.
- Never reviewing whether your diagnostic fee is covering cost. If your flat diagnostic fee was set several years ago and your labor rate has increased since, your diagnostic might be running at zero margin or below. Run Pass 1 quarterly: enter current labor rate, overhead, and drive time. If the suggested charge exceeds your current fee, your fee is underpriced — and crediting it is doubly bad.
Frequently Asked Questions
If I credit the diagnostic fee, should I show it as a line item on the invoice?
Yes. Show the repair at its full price, then show the diagnostic credit as a separate line: "Service call credit: −$165." This makes clear the repair is fairly priced on its own and the customer is receiving a defined discount, not a vague lower number. It also protects you if the customer later calls the repair overpriced — they can see exactly what they were charged for work performed and what was taken off as a goodwill credit. Transparency on credits is easier to defend than unexplained pricing.
Does crediting the diagnostic fee mean I'm discounting my labor rate?
Not technically — but the effect is similar. You're reducing total revenue on the combined job without reducing total cost. Whether you frame it as a labor discount, a fee waiver, or a credit doesn't change the math: less revenue, same cost, lower margin. The distinction matters for how you explain it to the customer. The diagnosis wasn't free and neither was the drive. The credit is a deliberate business choice to give back part of what you earned on the first pass. Own it as a choice, size it so it's viable, and don't make it a habit without checking the numbers each time.
The Bottom Line
Whether you keep the diagnostic fee, credit it, or partially credit it comes down to one number: combined margin on the full ticket. The diagnostic visit already cost you an hour, drive time, and overhead. That cost doesn't go away when the customer says yes to the repair. If the repair is large enough that a credit still lands at your margin target — or if you reprice the repair to absorb it — crediting makes business sense and can close a job efficiently. If the repair is small, the margin is thin, or you're crediting without adjusting the repair price, you're giving away real money with nothing in return.
Run two passes in the Job Profit Calculator: one for the diagnostic visit, one for the repair. Do the four-line combined math under each option. Then make the credit decision with actual numbers, not a vague sense that the customer deserves a break for saying yes.
All dollar figures in this article are made-up examples for illustration only. They are not claims about industry averages, prevailing rates, or typical job costs in any trade or market. This article is educational content about pricing methods — it is not legal, financial, or professional advice. Consult qualified professionals for guidance specific to your situation and jurisdiction.